


How mortgage rates shape US and NZ housing
Featuring
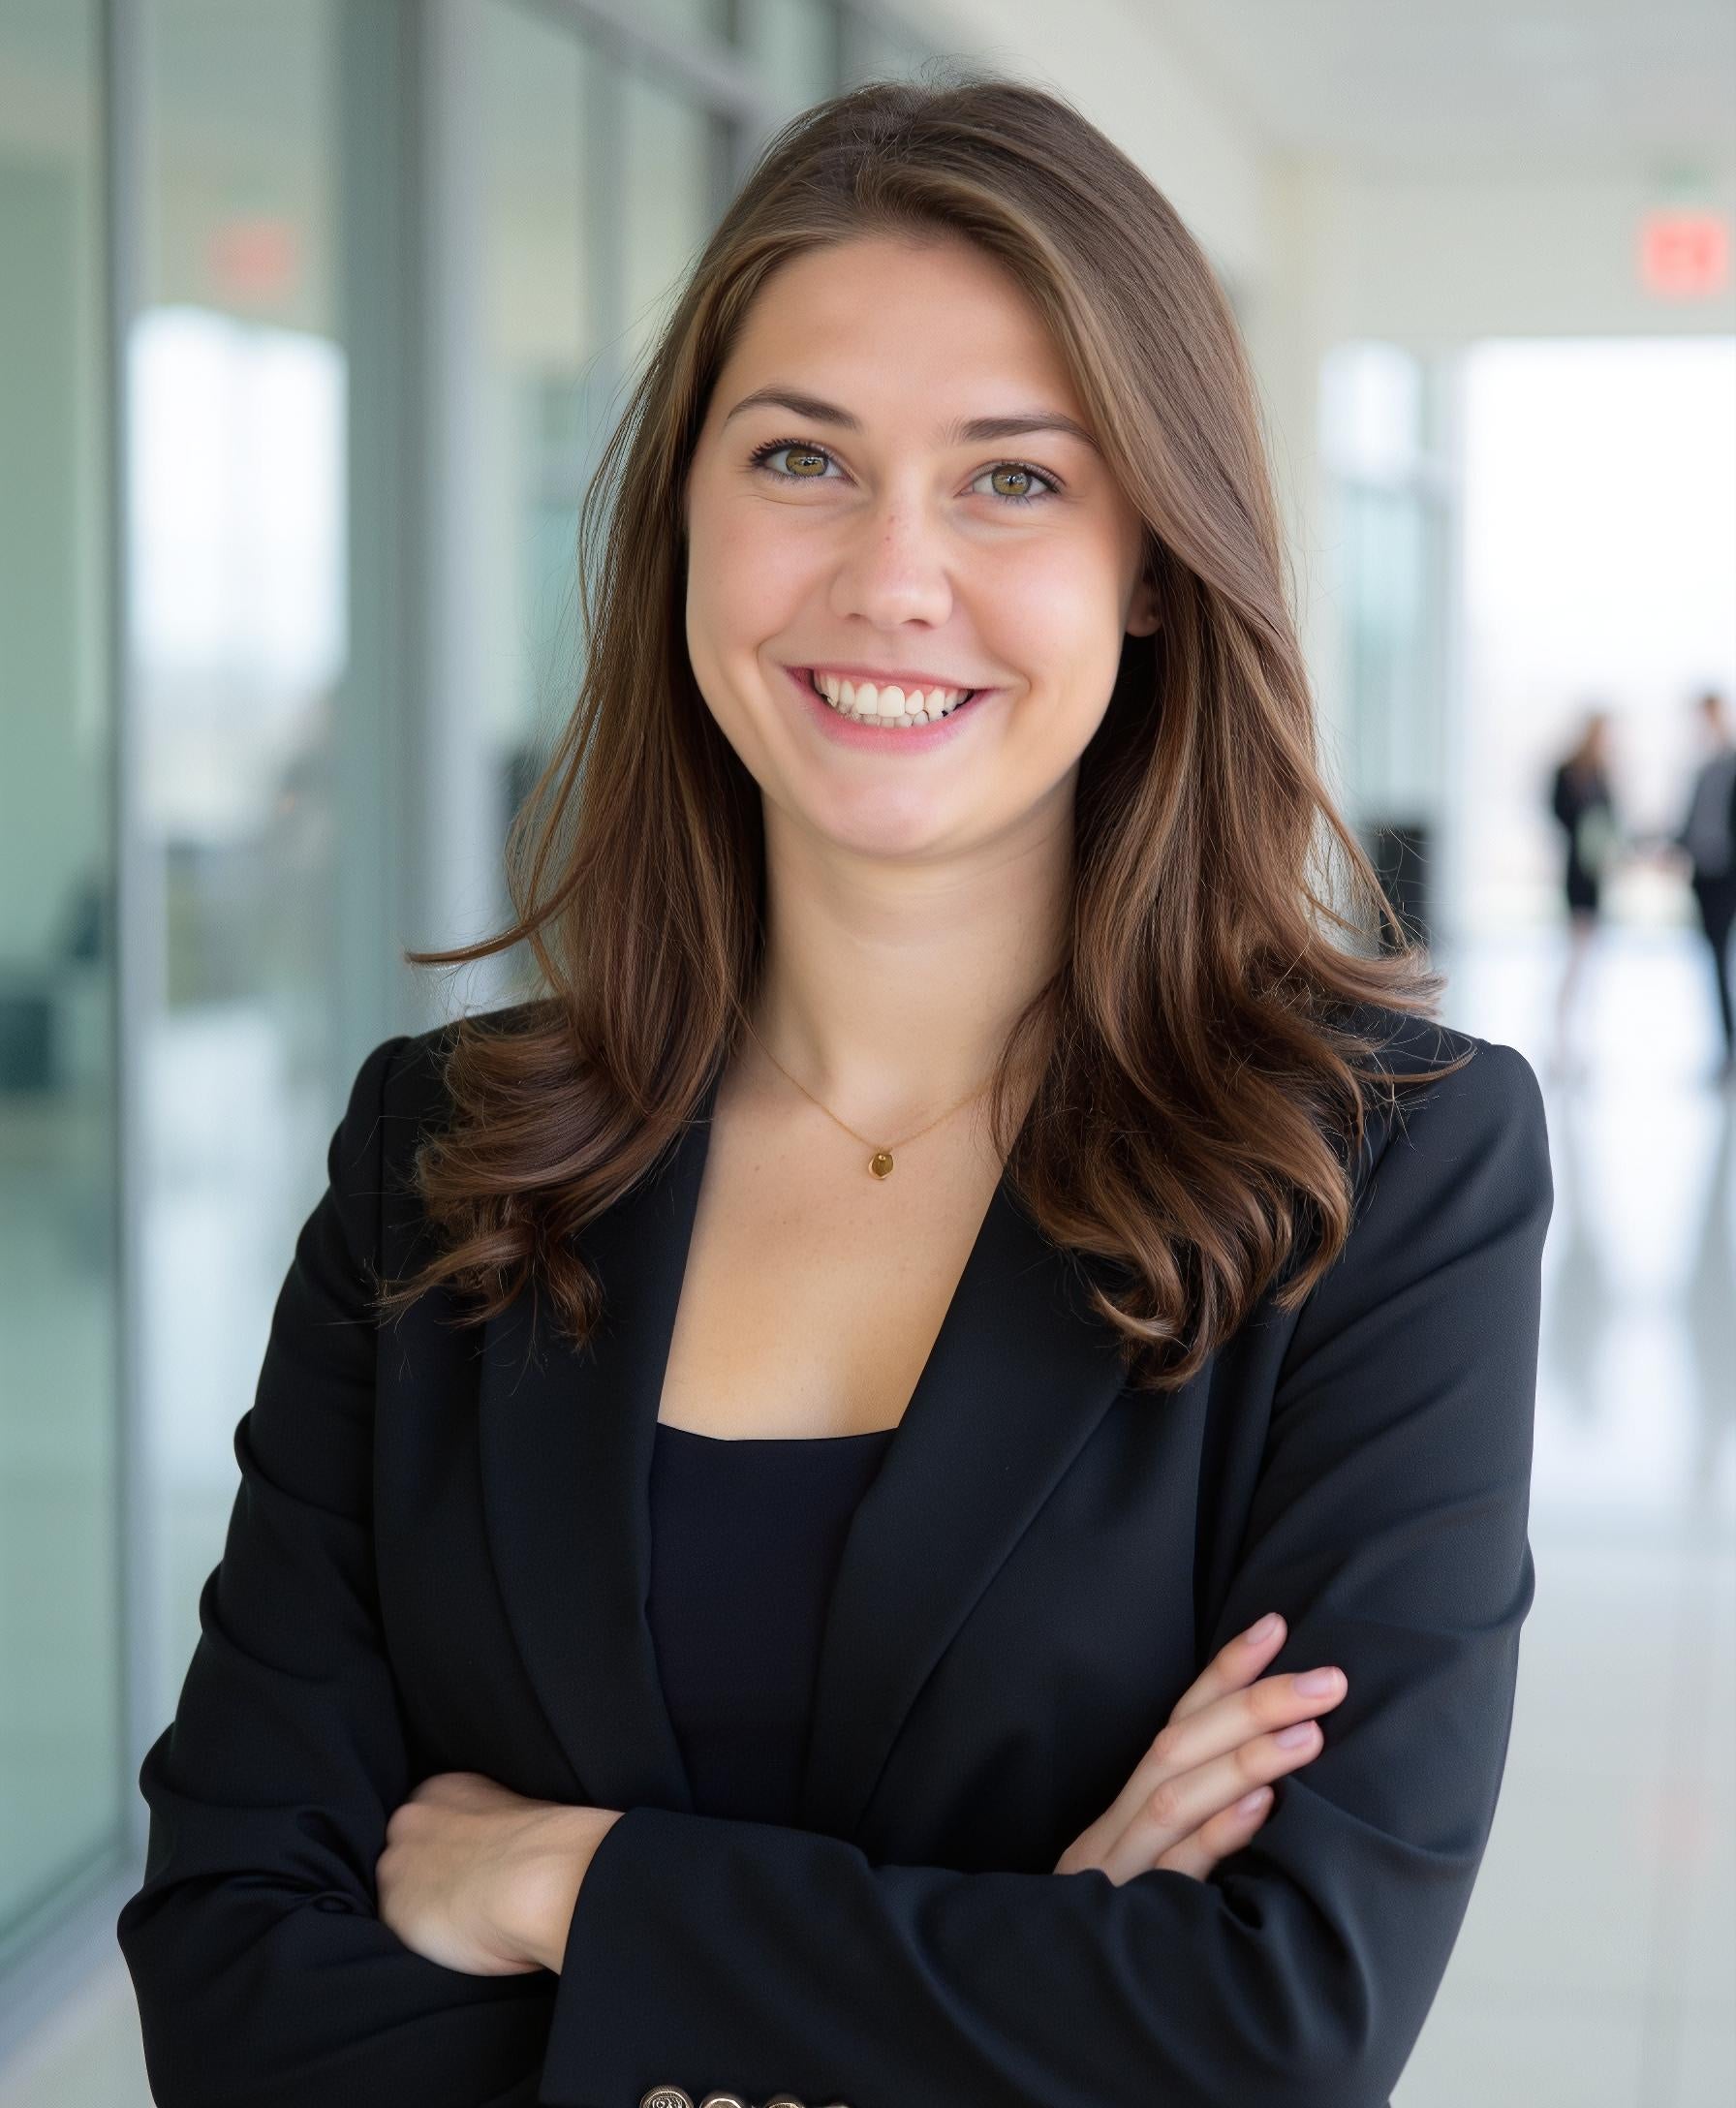
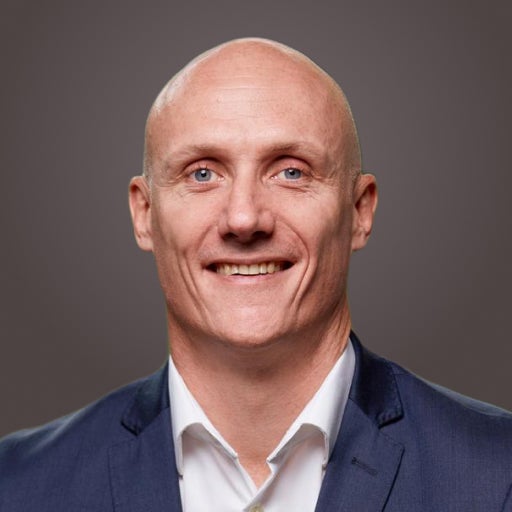
A conversation with Nick Goodall and Allie Barefoot
While both the U.S. and New Zealand face elevated borrowing costs, their housing markets are diverging along structural mortgage lines. In the U.S., the 30-year fixed-rate lock-in effect keeps homeowners from moving, whereas 90% of New Zealand mortgages are short-term fixed loans—meaning roughly 25% of Kiwi borrowers refix onto higher rates every six months.
Despite this pressure, Cotality data reveals that first-time homebuyers in New Zealand have surged to a 20-year record, accounting for 29.5% of Q3 sales. Pushed by high rents and aided by lower deposit allowances and urban densification reforms like the Auckland Unitary Plan, young Kiwi buyers are capitalizing on four years of flat home prices that have brought mortgage servicing costs down to 40% of household income.
Cotality's New Zealand Head of Research Nick Goodall joins Allie Barefoot to discuss differences and similarities of the U.S. and New Zealand housing market.
In this episode:
1:30 – Comparing the U.S. 30-year fixed-rate lock-in effect against New Zealand's short-term refixing wave.
4:23 – How four years of flat home prices pulled New Zealands's mortgage servicing costs down to 40% of household income.
6:02 – Why New Zealand first-time homebuyers hit a 20-year high of 29.5% of property sales despite high interest rates.
8:50 – Comparing U.S. housing market to Kiwi urban densification reforms.

Transcript:
Allie Barefoot: I’m Allie Barefoot with Cotality, and welcome back to Data in Context. Today, we are taking a global look at a shared housing crisis across two continents. In the U.S., mortgage rate volatility has struck again—sending 30-year fixed rates back up around 7% and deepening the inventory lock-in effect. But if you look across the globe, not every country is playing by the same financial rules. Let’s take New Zealand as an example. The country’s central bank rates sit at 2.75%, short-term fixed loans are resetting in the 5% to 6% range, and the entire housing debt structure is forced to adapt in real time. To help us look at the housing market numbers from a global perspective, I’m joined today by Cotality’s Senior Principal in New Zealand Market Research, Nick Goodall. Let’s put the Data into Context.
Allie Barefoot: Nick, thank you so much for joining us on Data in Context.
Nick Goodall: Oh, great to be here. Thanks for having me.
Allie Barefoot: Yeah, we're going to compare and talk a little bit about the US housing market and the New Zealand housing market. And I want to start off here kind of talking about the US as we're entering a period of structurally higher long-term interest rates, pulling 30-year mortgage rates back up around 7%. That surge is driving up contract cancellations and keeping American homebuyers really on the sidelines. And now switching over to the New Zealand housing market, I wanted to know, are you guys kind of having a similar experience with home buyer sentiment as you enter the spring market?
Nick Goodall: I think we're finding an interesting market right now. Our market has been slowing down for the last year or so, we've seen fewer transactions occur. We are seeing rising interest rates at the same time and that is part of the story. But very much a big part of this one is that our economy is not going so good and so consumer sentiment is not so great. Off the back of that, the jobs market isn't exactly ideal. And so people aren't sure about what's happening in their jobs, and so they're not necessarily acting in the housing market as much as they otherwise would if things were a bit better economically.
Allie Barefoot: No, totally makes sense. You know, in the US, the housing market has actually been locked up by the 30-year mortgage rate, which we found is pretty rare globally, with more than half of American homeowners holding rates under 4%. Nobody really wants to move with new rates sitting around that 7%. So, New Zealand has a totally different structure. The official cash rate is sitting at 2.75%, and short-term fixed-rate loans are resetting between that 5% to 6% range. So, how are Kiwi households absorbing that repricing pressure and are forced sales actually starting to show up?
Nick Goodall: Yeah, you're exactly right that we do have a very different market. About 10% of all mortgages are on a variable rate—floating rate where it just goes wherever the interest rates go and your payments will change immediately. But the other 90% is fixed relatively short term. And I think over a long, long period of time, New Zealanders would concentrate and focus more on the one- and two-year fixed rates, which as you said are around about that 5%, 5.5% rate right now. For many people, yeah, we came off an OCR of 2.25% earlier this year. As that's been going up, those interest rates are up. And now most people that are refixing the mortgage—and about 25% of all mortgages will refix in the next six months—they'll be doing so on higher rates. Typically though, they're managing to absorb this. We're not seeing really many forced sales or mortgagee sales at all. So yeah, people are managing to find a way to do this. They have had savings they can lean on and they'll adjust their spending elsewhere. And that's part of the story, right, why our economy is not going so well, is that yeah, people put more towards the mortgages and, especially with gas prices right now, they are spending less in the economy which means that we haven't had much economic growth so far this year.
Allie Barefoot: Yeah, you don't want to get me started on gas prices here in the United States. But it's very interesting to hear that Americans typically go for the 30-year fixed rate long-term, and then knowing that in New Zealand it's more of a one- to two-year short-term rate. Very interesting there. And with homeownership affordability pushed out of reach for many first-time home buyers, the US has seen a major push into build-to-rent communities. How is institutional capital in New Zealand responding to the rental demand? And are you seeing a rental shift toward these BTR projects—build-to-rent?
Nick Goodall: Yeah, I mean, build-to-rent is here. We do have it going on, there's a couple of really good projects that have gone to market, and they've so far been quite successful. I'd say it's still a relatively small scale, and I mean New Zealand is a small country in general, and then the build-to-rent sector is still quite small, but definitely an option. I think the government's also trying to get involved in this. We've had commitments from both of our major parties saying that they will assist the build-to-rent projects for those that are in community housing. So they've got an ability to try and get into the housing market. But what's really interesting is that we've actually had a really strong period for first-time buyers. In Q3 this year, we actually saw 29.5% of sales go to first-home buyers, and that's a record since we've been tracking it for more than 20 years now. So, first-time buyers have actually been managing to find a way. Part of the story is that they are exiting an expensive rental market, so they were paying quite a bit in rent. An ability or that benefit to go towards owning their own home and paying a mortgage instead has actually been quite beneficial. So, we've actually seen first-time buyers have a relatively good time of it, particularly while other buyers have been more cautious given the economic situation right now. So there's a few differences there, it's quite interesting.
Allie Barefoot:Yeah, that's great to hear about the first-time home buyer market. I mean that's a very high percentage for them to be able to enter the market, and even still be able to save up some money like you said with the rental market being so expensive to switch over to being property owners. And we've talked a little bit about the differences between the two countries in the housing market. So, I want to talk about a similarity here. Both countries are searching for structural fixes to affordability. In the US, there is a big push to streamline housing development processes and increasing construction counts, while in New Zealand, they have looked at loan-to-value ratio adjustments and first-time home buyer grant schemes. Do you think these demand-side incentives actually are helping everyday buyers? Or what is Kotality data showing for you?
Nick Goodall: Yeah, I think first-time buyers have got access to be able to get into the market with less than a 20% deposit, so the loan-to-value ratio restrictions you mentioned. The banks can still do lending below 20% deposit or above an 80% loan-to-value ratio. And at least half of all first-home buyers who get into the market are using that allowance. Outside of that, so not everyone needs that, so that means there is still an avenue for those people. They also can access their KiwiSaver funds. Now KiwiSaver is our not-quite-compulsory superannuation scheme where if you're an income earner, you automatically get enrolled in KiwiSaver. So you've got some money going towards your superannuation scheme, but you can tap into it to go towards your first-home deposit. And so that's a really strong support to get those first-time buyers into that market. Those first-home buyer grant schemes, they've sort of changed quite a bit over the last few years as well, so they do still exist in some places, but they're not quite as strong as they were in the past. From a demand side, it does help those first-home buyers. So we do see numbers lift off the back of that.
But interesting you talk about, you know, consents and building as well. I think that's the core thing for affordability: to build more homes, and particularly in Auckland. We had what was called the Auckland Unitary Plan put in place in about 2018. And what that did was enable builders, developers, people to build more properties on the same piece of land. So go more intensification, more densification. They absolutely made the most of that. We built more properties in a short space of time. And that has really helped keep affordability much better than it would have otherwise been had something like that not been in place. We are seeing versions of that around the rest of the country as well. And that has led to less house price growth say over the last decade than I think what we might have otherwise seen, which means that those properties are accessible to those first-time buyers, particularly for somewhere like Auckland, building a lot more townhouses. And those are priced much more affordably for those first-time buyers to get into the market. So I think that's a strong solution as well.
Allie Barefoot: Yeah, absolutely, knowing that stretched inventory is also something that we're dealing with here in the US and our housing market as well. And looking forward for both the US and New Zealand as they continue to grapple with affordability limits, high carrying costs, and, like you said, tight supply: what is the single biggest structural shift or policy reform that, in your opinion, needs to happen to move that needle for everyday home buyers heading into 2027?
Nick Goodall: Yeah, I mean, as I said, I think because first-time buyers have been pretty active, the market's actually quite favorable for them. While affordability had been really stretched a while ago, it's actually improved a lot. Particularly, the number I look for is the proportion of income required to service a mortgage. And the main reason we look at that one ahead of say something like a simple value-to-income ratio is because that proportion of income required to service a mortgage also includes what the interest rate is at the time. And so given most people use a mortgage to buy a property in New Zealand, then that's a really strong measure. And right now that's actually sitting below the long-term average. So about 40% of income is required to service a mortgage right now. It got to about 51% at the peak of the market in 2021, so we might be a little bit different there where our affordability's actually really improved. I know in Australia right now they're certainly much more stretched, they're closer to that 50% for many cities around Australia. But for us it's actually not too bad right now when we haven't seen really any house price growth for about four years. And so that market is actually really favorable at the moment. So I think there's a bit of a difference there.
I think what we are watching for next year is when we do see economic growth improve, when the jobs market improves as well and unemployment reduces, that's when I think that confidence will come back and we might actually see a lift in prices. Though we do expect that that rate of growth will be much more contained than what we've seen in the past, much closer to 3% as opposed to something in the past which was closer to 6% on average for an annual growth rate.
Allie Barefoot: Yeah, that's definitely something we're going to have to keep an eye on as we move into 2027. And Nick, this was super insightful to be able to compare and really look at both housing markets, both in the US and New Zealand, and see where affordability is the same, but different in both of our areas. So, thank you so much for taking the time to break down Kotality's data with us today.
Nick Goodall: Yeah, you're very welcome. Great to be here. Thanks so much for having me.
Allie Barefoot: Of course. Thank you again to Nick for joining me on Data in Context and thank you so much for listening. If you haven't already subscribe to Cotality's YouTube channel, and as always, if you want to find out more information about the United States or New Zealand, head on over to Cotality.com
Related Resources

