


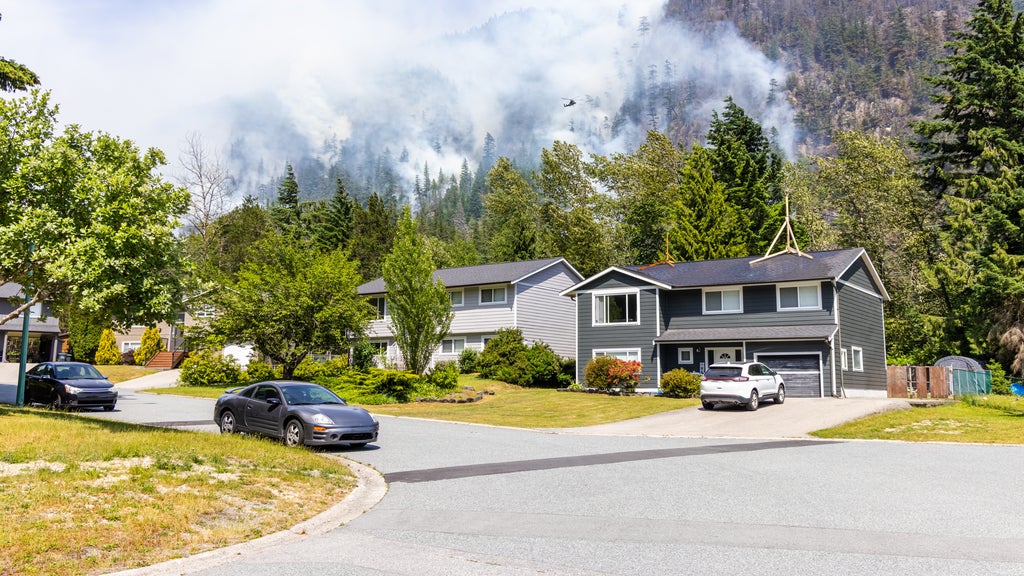
Overview

The science of structure survival during a wildfire is remarkably settled. Decades of post-fire research point to the same conclusion: whether a home survives is determined largely within the Home Ignition Zone, the building itself and the immediate 100-foot perimeter around it. Homeowners can act on that zone today. The harder question has always sat on the carrier side of the equation: how to verify that work at the address level and reward it defensibly. Cotality calls this unresolved question the incentive gap.
What is the wildfire incentive gap?
The incentive gap is the disconnect between what homeowners can do to reduce wildfire risk and what insurers have historically been able to verify and reward. Without address-specific data on parcel conditions and structural hardening, carriers lacked a defensible basis for granting premium credits, and filed rates could not distinguish a hardened home from an untouched one next door.
The result is a damaging cycle. Without financial reward or awareness of the risk, homeowners invest little in mitigation. Risk stays elevated. Carriers retreat from exposed markets, and policies pour into overburdened state residual markets that were never designed to carry that volume. Every participant loses, including the carriers that exit growth markets they could otherwise serve profitably.
How do property-level mitigation scores work?
Address-specific analytics break the loop. A property-level mitigation score, scaled from 0.1 to 100, combines community protections, parcel conditions, and structural hardening into a single, defensible input for underwriting and pricing. Two high-leverage signals carry the strongest weight:
• Noncombustible zone 0: maintaining a 0- to 5-foot ember-resistant perimeter around the foundation, where wind-blown embers most often accumulate against a structure
• Class A roof verification: confirming top-tier fire resistance on the surface most exposed to ember accumulation
These signals reflect a broader truth from fire research: embers, not flame fronts, ignite most homes lost in wildfires. Scoring the places embers land makes mitigation measurable, and measurable mitigation is what rate filings require.
What does the actuarial evidence show?
A Cotality analysis of 6.8 million single-family residences, using a mitigation scoring methodology approved for insurance rating use in California, demonstrates that modeled loss costs fall exponentially as mitigation improves.
Homes in the top 10% for mitigation carry expected losses roughly 78% below the statewide average. Homes in the bottom 10% run more than 10 times the average, about $47 in expected loss for every $1 on the best-prepared homes. Few variables in property insurance produce a spread that dramatic, and it gives underwriters a scientifically grounded, regulator-ready basis for segmenting and pricing wildfire risk.
What do regulators now require?
Regulatory frameworks increasingly mandate what the data supports. California’s Safer from Wildfires regulation requires premium discounts for verified mitigation. Colorado’s House Bill 25-1182 goes further: carriers using wildfire risk scores must disclose them, credit parcel- and community-level mitigation, and give homeowners a formal channel to appeal incorrect scores or uncredited improvements. For carriers operating in these states, address-level mitigation data is shifting from competitive advantage to compliance infrastructure.
Closing the incentive gap benefits every participant in the market. Carriers gain the data confidence to keep writing, and to grow, in exposed regions where competitors have imposed blanket moratoriums. Residual markets shed volume they were never built to hold. Homeowners gain a clear financial return on hardening investments, and communities gain neighborhoods where mitigation spreads house by house, reducing the fuel available to the next conflagration.
For the full analysis of mitigation economics and the other systemic gaps shaping wildfire risk, read the 2026 Cotality Wildfire Risk Report.
