


The growing threat of AI altered documents in mortgage underwriting
Featuring
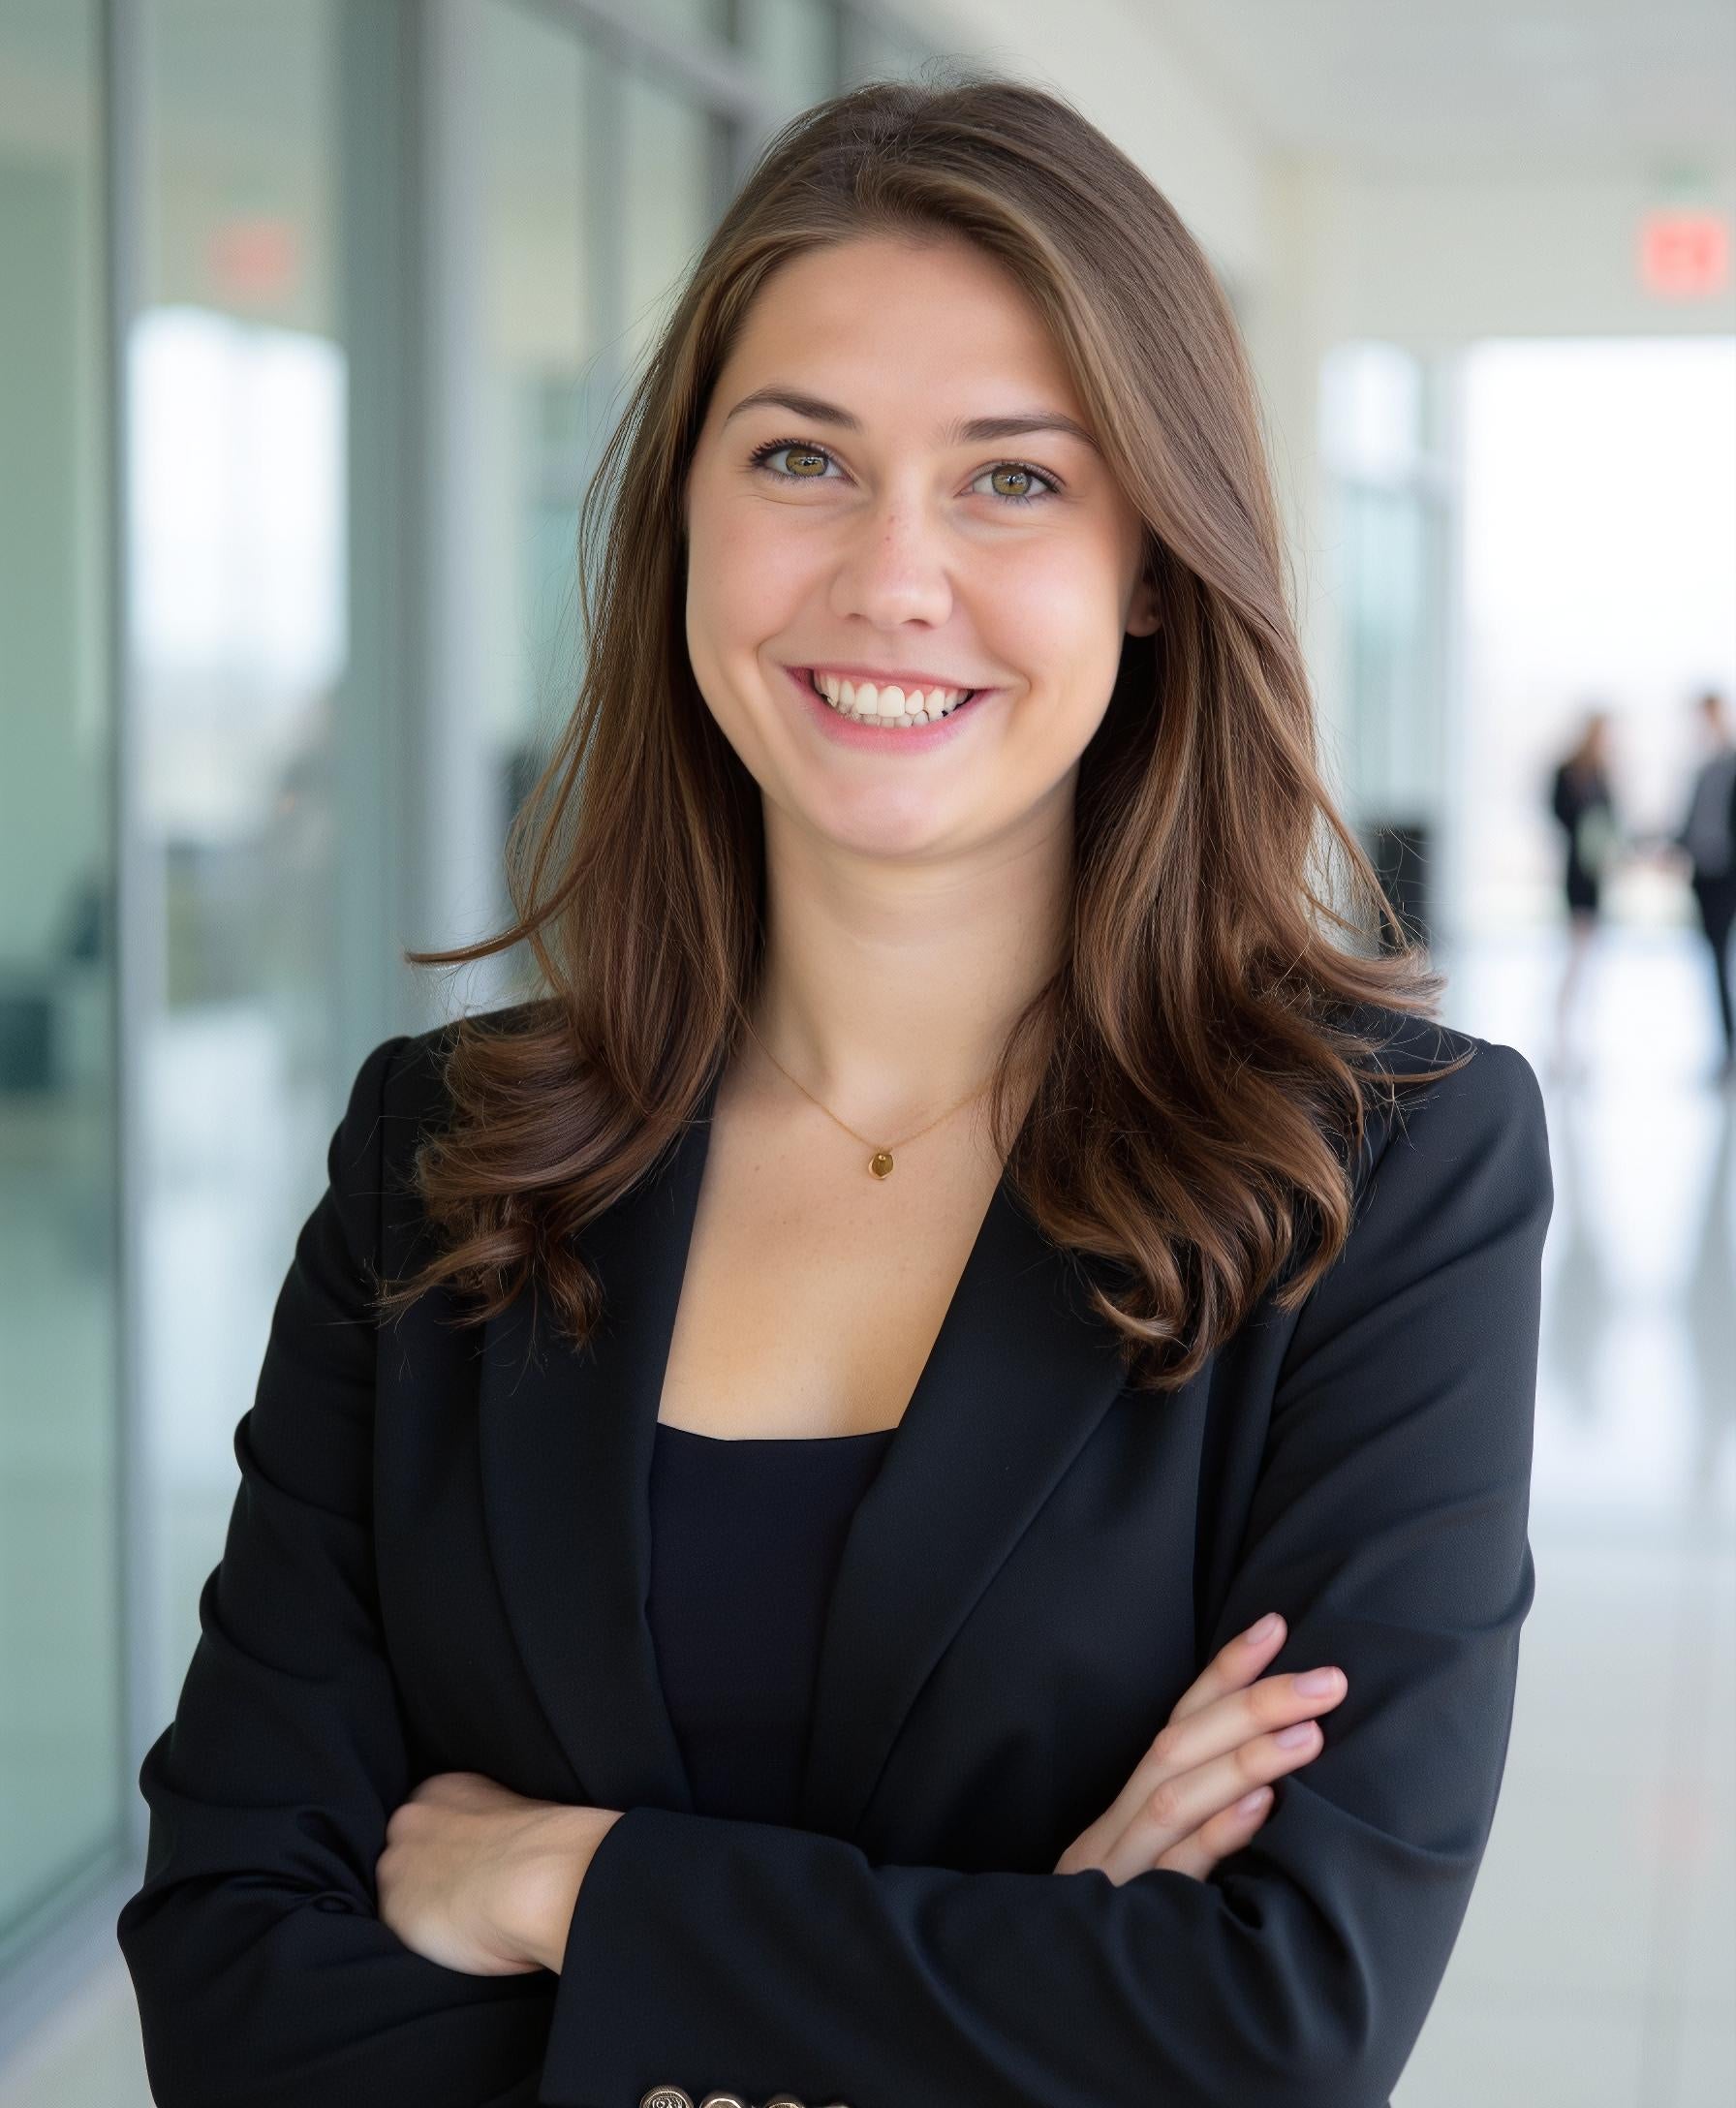
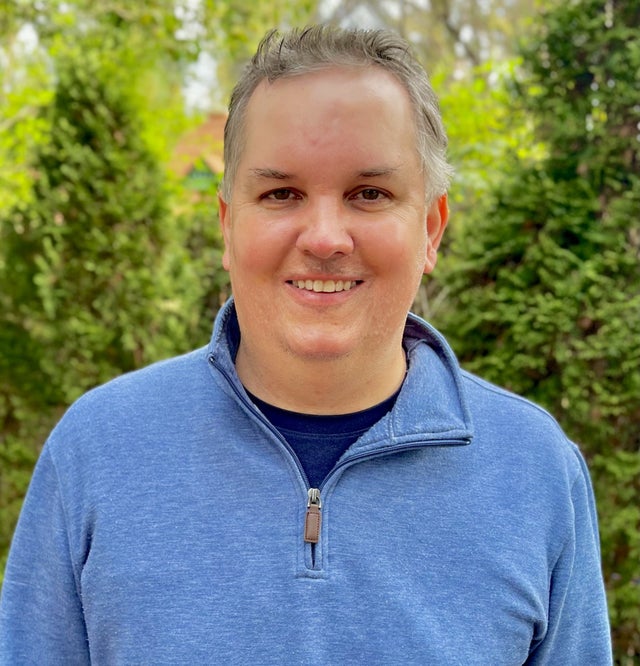
A conversation with Matt Seguin and Allie Barefoot
The recent annual report from Cotality highlights a compelling paradox in current real estate trends: while overall annual fraud risk dropped 4.6% year-over-year, quarter-over-quarter fraud risk surged by over 9% in Q2 2026 alone. As elevated interest rates stifle refinancing activity, the market has shifted dramatically toward purchase transactions, bringing a fresh set of fraud vectors.
This market pivot has exposed vulnerabilities, notably a spike in undisclosed mortgage debt, hyper-targeted investor risks, and the emerging shadow of AI-altered documents. Traditional document checks are increasingly unable to detect these high-tech manipulations, leaving lenders facing unprecedented compliance and financial exposures.
In this episode, host Allie Barefoot sits down with Cotality’s Senior Principal in Product Management, Matt Seguin, to discuss how lenders can move beyond single-document verification toward portfolio-level pattern analysis to safeguard their assets.
In this episode:
2:11 - How is generative AI changing document manipulation and detection in mortgage applications?
4:37 - How does Cotality collect and calculate data for its LoanSafe platform and FraudRisk Index?
5:51 -What is driving the high fraud risk in investment and multi-unit properties?
7:48 – How can lenders protect themselves against sophisticated pattern fraud?

Transcript:
Allie Barefoot: Welcome back to Data in Context. I'm Allie Barefoot with Cotality. When you look at headline mortgage numbers, it's easy to miss the shifting risk beneath the surface. According to Cotality's latest annual fraud report, overall fraud risk dropped 4.6% year-over-year. But that's only half of the story. Quarter-over-quarter, fraud risk actually jumped over 9% in Q2 2026 alone. As interest rates stay elevated, refinances have dried up, forcing a massive shift toward purchase volume. And with that shift comes a whole new set of fraud vectors. We're seeing a massive rise in undisclosed mortgage debt risk, hyper-targeted investor risks, and a growing shadow of AI-altered documents that traditional checks just can't reach. So today, we're joined by Cotality's Senior Principal in Product Management, Matt Seguin, to look at how lenders can protect their portfolios. Let's put the data into context.
Allie Barefoot: Matt, welcome in to Data in Context.
Matt Seguin: Hi, Allie. Thanks for having me.
Allie Barefoot: Of course. Cotality recently just launched their 2026 annual fraud report, and I want to start with a headline statistic. The Cotality Fraud Risk Index closed out Q2 2026 at 132, which translates to about 1 in every 119 applications showing indications of fraud. Walk us through what drove that 9% quarter-over-quarter jump from Q1.
Matt Seguin: Sure, I'd love to do that. So that 9% jump from the prior quarter is really due to a large increase in the purchase volume. In quarter one 2026, we saw purchase volume at 59%. That actually jumped up to 72% in Q2. So the driver there is obviously the rise in interest rates, which has limited the amount of refis, and then we layer on historically that purchases have higher fraud risk.
Allie Barefoot: And Matt, we can't talk about modern fraud without mentioning generative AI. I feel like it's coming up in almost every single conversation I have nowadays. So how is the evolution of tech altering document manipulation?
Matt Seguin: Yeah, I agree. That is a very hot topic, Allie. So 25 years ago, it was literally physical Wite-Out. Then it evolved into basic PDF editors where fraudsters could make the changes, but they would often leave something for the underwriters to be able to find. Maybe it's a misaligned date, a typo, a math error. But now AI has basically made an altered PDF virtually undetectable. Those human telltale signs have just disappeared. There are some vendors out in the market claiming they can identify altered PDFs, and while I haven't tested those myself, the clients I've spoken to who have, the industry feedback I've heard in committee meetings, has stated that right now that technology just isn't there consistently, at least, to identify those. And it seems the tech is just moving too fast to catch up to the altered PDFs at this point.
Allie Barefoot: Yeah, sometimes it does feel like that tech is moving just a little bit too fast. And I think the connection between interest rates and fraud risk is really fascinating. You know, looking back over 16-year data sets that Cotality has, why do low-rate environments keep fraud down, while high-rate environments push it up?
Matt Seguin: So it's really about opportunity. And when I say opportunity, think about documentation in the file. So during those low-rate periods, specifically the COVID era is a good example, refis surged, particularly government streamline programs. And a lot of those programs don't require income, appraisal, asset documentation. So fewer required documents just simply means fewer opportunities to commit fraud. Another reason for that, and it's less quantifiable, is that when borrowers are more easily qualified from a DTI perspective because of the lower rates, the bad actors—the fraudsters—they don't have as much motivation, really, to risk altering documents to get a deal done.
Allie Barefoot: Yeah, I thought it was really interesting what you said there about fewer required documents means fewer opportunities for fraud risk. And I think I want to go a little bit behind the scenes here: How does Cotality actually produce this data? You know, what's happening, especially with something like the LoanSafe platform?
Matt Seguin: So yes, Allie, I'd be happy to do that. So the index is built by aggregating data across the millions of LoanSafe reports run by our consortium clients. What really sets our fraud risk score apart is it's using machine learning. It's a model trained over the last 15+ years. It's based on millions of applications and tens of thousands of confirmed fraud—what we call client-reported fraud tags. So today, the score ranges from 1 to 999—1 being the least risky, 999 being the most risky. And what we're really targeting is precision. What we're seeing in the data today is 55% of those confirmed fraud cases score 800 or higher. Yet that high-risk category only represents about 10% of the applications. So we're really trying to give our clients a targeted map of where to focus their resources.
Allie Barefoot: And let's take a look at some of the specific categories here. Out of the six primary fraud categories Cotality tracks, undisclosed real estate debt was the only one that increased. At the same time, our report highlights investment properties around 2-to-4 unit buildings as the absolute riskiest segments overall. What's happening in this category, and how stark is that risk gap?
Matt Seguin: Yes. So let me start with the investment in 2-to-4 unit applications. That gap is significant. Risk on these properties is typically about three times higher on average than the typical baseline. And we mentioned earlier, 1 in 119 applications is the baseline. Investment properties is at 1 in 44, and 2-to-4 unit properties is at 1 in 27. So that's where you see that real significant gap between those. Going back to what you started with, the undisclosed real estate debt, that was actually something that we've looked at really closely over the last year. And what we found is alerts driving this category [are] about two and a half times more likely to fire on an investment property versus an owner-occupied property. Now, at that same time that that's been happening, the investor and 2-to-4 unit property application volume has really gone up. In 2024, that represented about 8% of our overall volume. In the middle of 2026, we're up to 12%. So we're seeing a 50% increase. So when we have the application volume growing in the investor space, that is inevitably going to drive higher undisclosed real estate... undisclosed debt real estate risk alerts because those investors are just really more prone to own multiple properties and more likely omit existing debt obligations.
Allie Barefoot: Yeah, that makes sense. And Matt, to kind of round out this conversation here, if single document verification is becoming a game of cat and mouse, what do lenders actually need to do in order to protect themselves?
Matt Seguin: Yeah, that is no doubt a challenge, Allie. And what I like to recommend to our clients is really the shift of focus a bit from the individual document inspection to more portfolio pattern analysis. And you really start aggregating the data that you have, whether it's across brokers, loan officers, realtors, sellers... You know, there's many options that you could do there. And then within that, are you seeing clusters of self-employed borrowers with similar income? Maybe repeated transactions tied to a seller? Those are just some of the red flags that you could start looking for that could be really worth taking a deeper dive into. If I think back to about last May—so May 2025—Fannie Mae and Palantir partner... It was a very public partnership that came out, and it seems to be a clear signal that the GSEs are really moving a little bit towards that pattern detection technology. When I think of pattern fraud, and from the lender's perspective, now that that one repurchase, which is already costly, could turn into multiple repurchases—maybe it's three, maybe it's five, whatever they're able to turn up in that systemic pattern fraud—it's actually why we built a tool here at Cotality called LoanSafe Explorer, which can really help our clients proactively spot fraud patterns earlier in the process.
Allie Barefoot: Yeah, no, that's definitely great advice. And I'm sure that there is a lot more information in the annual fraud risk report. But I really appreciate you taking the time just to dive a little bit deeper here with these questions with me today, Matt.
Matt Seguin: Yeah, happy to do it, and I encourage everyone to go out and read that fraud report. Thank you.
Allie Barefoot: Absolutely. Thank you again to Matt for joining us here on Data in Context, and thank you so much for listening. If you haven't already, go on ahead and subscribe to Cotality's YouTube channel. And if you want to find out more information, Cotality's annual Fraud Risk Report is now live at cotality.com.
Related Resources

